What Is Public Liability Insurance?
Public liability insurance is designed to protect your business if your activities cause injury to another person or damage to property belonging to someone else.
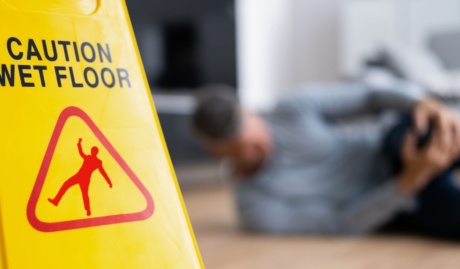
Claims can arise in all sorts of everyday situations. A customer could slip and injure themselves at your premises, you could accidentally damage property while working at a client’s site, or a member of the public could be injured as a result of work your business is carrying out.
Depending on the policy and circumstances of the claim, public liability insurance may help cover compensation you become legally liable to pay as well as certain legal and defence costs.
For businesses that regularly interact with customers, suppliers, contractors or members of the public, it can form an important part of broader business insurance cover.
AIB can help you find a policy tailored specifically to your business needs, industry and budget.
What Is Product Liability Insurance?
Product liability insurance helps protect businesses against claims arising from products they manufacture, import, distribute, supply or sell. For example, a claim could arise if a product causes injury to a customer, damages their property or is alleged to be unsafe or defective.
Product liability exposure isn’t limited to manufacturers. Retailers, wholesalers, importers, distributors and online businesses may also face claims relating to the products they supply.
Cover is therefore particularly important for businesses involved in bringing products to market, especially where those products could cause injury or property damage if something goes wrong.
Businesses with greater product exposures can also read our guide to product liability insurance for high-risk businesses.
Public Liability vs Product Liability Insurance
Public Liability Insurance
Product Liability Insurance
Relates primarily to your business activities and interactions with third parties.
Example: a customer slips and is injured at your premises.
Example: you accidentally damage a client’s property while performing work.
Relates primarily to products your business manufactures, supplies, imports or sells.
Example: a product you sell causes injury or property damage.
Example: a faulty product causes a fire and damages a customer’s property.
Do businesses need both?
Public and product liability are commonly provided together because many businesses have exposure to both types of risk. A retailer, for example, may have customers visiting its premises as well as liability associated with the products it sells.
An AIB broker can help you identify which exposures apply to your business and arrange appropriate cover.
What Does Public and Product Liability Insurance Cover?
Public and Product Liability insurance will generally cover the costs of investigating, defending and settling claims made against your business as well as any compensation that you are found liable to pay. It can even cover emotional distress or shock that your business causes another person. Some of the things your policy may cover you for include:
- Loss or damage to someone else's property while you are delivering your service
- Personal injury to others who may be visiting your premises
- Injuries sustained by others whilst using you product
- Loss or damage to goods that you do not own that are in your care or custody
- Somebody acting on behalf of your business when the incident occurred
- Legal costs incurred in investigating, defending or settling a claim
- Liability arising out of advertising carried out by or on behalf of the insured
The exact cover, limits and exclusions vary between policies and insurers. This is one reason why comparing policies on price alone can leave important gaps in protection.
What Isn't Usually Covered?
Public and product liability insurance isn’t designed to cover every type of business risk. Depending on the policy, exclusions or separate insurance requirements may apply to:
- Injury to your own employees
- Professional advice, design or specification errors
- Damage to your own property
- The cost of fixing or redoing your own faulty work, or repairing or replacing a defective product itself
- Claims involving registered vehicles, aircraft and larger watercraft
- Asbestos-related claims and most pollution events
Other insurance policies may be required for these exposures. For example, businesses providing professional advice may also need Professional Indemnity Insurance, while employee injuries may fall under workers compensation arrangements.
Always refer to the relevant Product Disclosure Statement and policy wording for full details of cover, limits, conditions and exclusions.
Who Needs Public Liability Insurance?
While Public Liability Insurance isn’t mandatory for most businesses, it is one of the most valuable business insurance policies you could invest in.
Public liability insurance can be relevant to businesses of almost every size, particularly where your work brings you into contact with customers, members of the public or property belonging to other people.
Businesses that commonly consider public liability cover include:
- trades and contractors
- builders and construction businesses
- retailers and wholesalers
- cafés, restaurants and hospitality businesses
- health, fitness and wellbeing providers
- tourism and accommodation operators
- professional and service businesses
- manufacturers and distributors
- sole traders and small businesses.
Even if you are the most careful of operators, unforeseen accidents happen all the time. As a business owner, if you were faced with a public or products liability claim, the financial impact could be catastrophic. Aside from the cost of legal fees or compensation payments, the chances are you would also face issues with business interruption to your business as well as damage to your reputation.
You should strongly consider Public and Product Liability Insurance if:
- you have visitors to your premises or
- you deliver services to clients or customers in public spaces or at their premises or
- your work involves a customer’s property or
- you manufacture or sell products or services
- you use sub-contractors or labour hire personnel in your business or
- you lease or use a business space
At AIB we can tailor insurance packages suited specifically to your needs. As business insurance experts, we can find policies, negotiate insurance contracts and create bespoke packages, regardless of your industry.
Public Liability Insurance for Small Business
For a small business, even a single liability claim can have a significant financial impact. Legal costs, compensation and disruption to your operations can quickly become difficult to absorb without appropriate insurance.
Whether you’re a sole trader, run a small team or operate from your own premises, your liability exposure depends on what your business actually does rather than simply its size.
AIB can help small business owners assess their risks and find public liability cover appropriate to their activities and budget.
How Much Does Public Liability Insurance Cost?
There is no single price for public liability insurance because premiums are calculated according to the risks associated with an individual business.
Factors that can affect the cost of cover include:
- the type of business you operate
- the activities you undertake
- annual turnover
- the number of employees
- whether you use subcontractors
- where you carry out your work
- the products you manufacture or sell
- your claims history
- your required level of cover
- any higher-risk activities or exposures.
A lower premium doesn’t necessarily mean better value. Policy limits, exclusions, excesses and the scope of cover should also be considered when comparing options.
Do You Need Public and Product Liability Insurance?
Why Use a Public Liability Insurance Broker?
Buying liability insurance isn’t simply about finding the lowest premium. Differences in cover, exclusions, excesses, insurer appetite and policy wording can have a major impact when you actually need to make a claim.
A public liability insurance broker can help you:
- identify the liability risks associated with your business
- understand the type and level of cover you may need
- approach suitable insurers
- compare policy options and exclusions
- arrange documentation and Certificates of Currency
- review your cover as your business changes
- assist you if you need to make a claim.
AIB works with a range of insurers to help clients find appropriate cover rather than being limited to the products of a single insurer.

What is public liability insurance?
Public liability insurance protects your business if a member of the public is injured or has their property damaged as a result of your business activity. It helps cover legal costs and compensation, reducing the financial risk of unexpected claims.
What does public liability insurance cover?
This insurance typically covers compensation for personal injury or property damage caused to third parties by your business operations. It also covers legal defence costs if a claim is made against your business.
How can I get public liability insurance?
You can arrange public liability insurance through an insurance broker like AIB Insurance Brokers. We work with multiple insurers to compare policies and provide tailored insurance solutions to suit your business needs.
Do I need public liability insurance?
While public liability is not compulsory for most businesses in Australia, there are some exceptions. It depends on the state or territory you are in. Certain trades like electricians and plumbers in Qld require public liability cover to obtain or renew their license. For more information about Queensland-specific requirements, see our guide to Public Liability Insurance in Qld.
An AIB broker can help you understand the obligations based on your industry, location and contractual obligations.
Do I need public liability insurance as a sole trader?
Yes – sole traders are just as exposed to liability claims as larger businesses. If your work involves any interaction with clients, members of the public, or property not owned by you, public liability insurance offers valuable protection. In addition, if you work in certain trades then it is compulsory in some states and territories.
What’s the difference between public and product liability insurance?
Public liability insurance covers injury or property damage to third parties occurring in the course of your business operations.
Product liability insurance covers injury or property damage caused by products your business supplies or manufactures.
What is product liability insurance?
Product liability insurance covers your business for claims made due to defective products that cause injury or damage. It provides protection for manufacturers, distributors, and retailers against consumer lawsuits related to product faults.
Is product liability insurance compulsory?
Product liability insurance is generally not legally required but may be necessary under some contracts depending on your state or territory. It is, however, strongly advised to obtain product liability insurance – especially if your business manufactures, distributes, or sells products – since product-related claims can be costly.